
Elon just asked for 1,000,000 satellites (From Behind the Markets)
Key Points
- S&P 500 earnings growth is expected to slow in Q3, but substantial upside surprises in Q1 and Q2 leave room for another beat.
- Cybersecurity stocks, including Palo Alto Networks, CrowdStrike, and Okta, are seeing accelerating revenue growth and rising analyst price targets as AI drives security demand.
- Marvell raised long-term guidance at its Oct. 6 Investor Day, while analysts have grown increasingly bullish on Intel and AMD amid rising CPU demand for AI inference.
- Special Report: Nvidia pours 7 billion into a light speed AI breakthrough (From Brownstone Research)
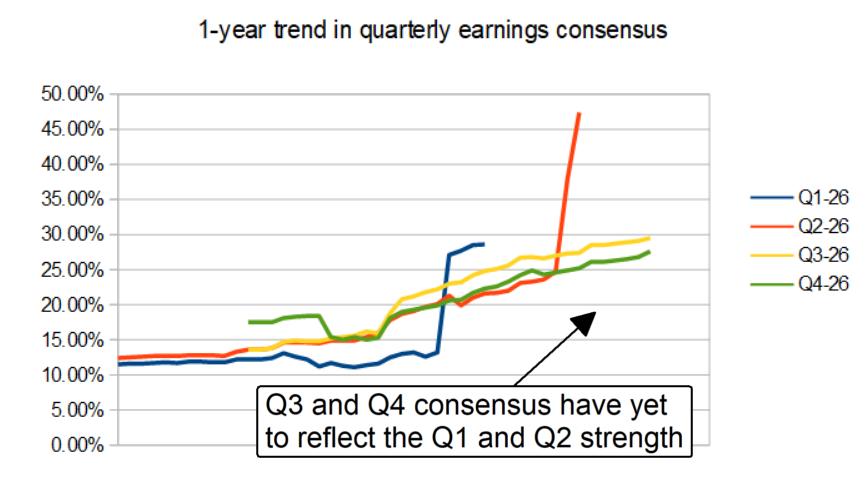
Average S&P 500 earnings typically beat consensus in Q3, as the market has historically done. The S&P 500 tends to outperform by a modest single-digit figure, but that’s not the case in 2026. Average earnings could again blow past consensus because results to date reveal a disconnect. Q1 outperformance topped about 1,500 basis points (bps), and Q2 widened the gap to roughly 2,700 bps, a trend that could continue this quarter.
Consensus in early October is for a slowdown to about 29.5% growth, down from roughly 50% in Q2. Given the robust outperformance in Q1 and Q2, trends such as AI and high oil prices, and the relatively modest increase in Q3 estimates, the odds favor another beat. A move into the +50% range would require another unusually large upside surprise.
Ian Cooper Unveils a Simple Options Trade Strategy (Ad)
Ian Cooper's newest strategy targets triple-digit returns in just 9 days. It doesn't work every time, but a 73% win rate and 2,671% return on capital stand on their own.
Ian is breaking down the full strategy and offering his newest report at no charge.
Get the free report and see the full options strategy now
Cybersecurity Stocks Flip the SaaS-Pocalypse Narrative
SaaS-Pocalypse fears, fear of AI disrupting software providers across the board, including cybersecurity stocks, were increasingly looking misplaced. The narrative in late 2026 is that AI, and more specifically agentic automation, is driving business for vendors across the board, especially for cybersecurity stocks. Agentic AI drives a sharp increase in traffic and security needs at all levels, with no aspect unimportant. This has made unified cybersecurity platforms and ecosystem partners increasingly in demand, as reflected in analysts' revisions.
Analysts are aggressively increasing price targets for cybersecurity stocks. Companies like Palo Alto Networks (NASDAQ: PANW), the industry-leading pure-play, CrowdStrike (NASDAQ: CRWD), and Okta (NASDAQ: OKTA) are seeing revenue growth accelerate, with internals pointing to momentum and potential for outperformance over the next several years. NVIDIA (NASDAQ: NVDA) is among the drivers, especially with its GPUs and industry-specific focus on security, partnering with a variety of technology providers to embed security throughout its AI ecosystem.
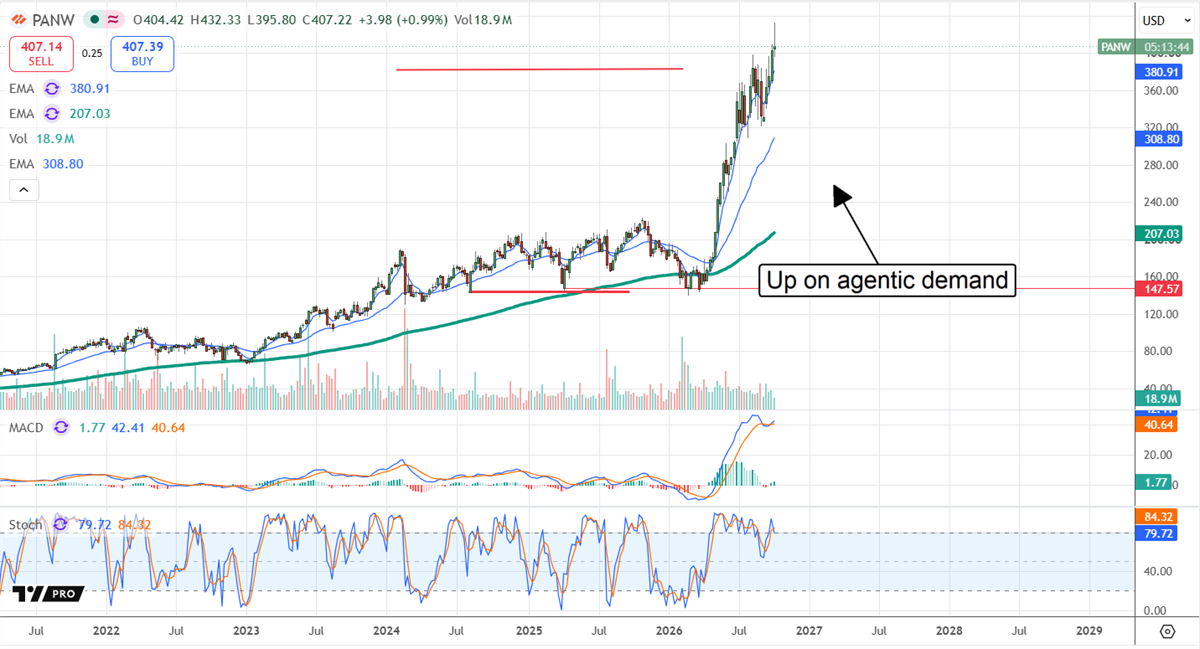
Cybersecurity demand is broad-based across industries and verticals. PANW’s CEO Nikesh Arora estimates that $1 trillion of legacy security infrastructure needs to be modernized for the AI era. Systems installed even a few years ago can’t handle the speed and scale of attacks, which are lightning-fast and target every available pathway, with multiple agents often working cooperatively to exploit vulnerabilities. This sets the stage for strong, accelerating, and sustained cybersecurity demand.
Marvell Aggressively Ups Targets, Provides Multiyear Visibility to AI Spending
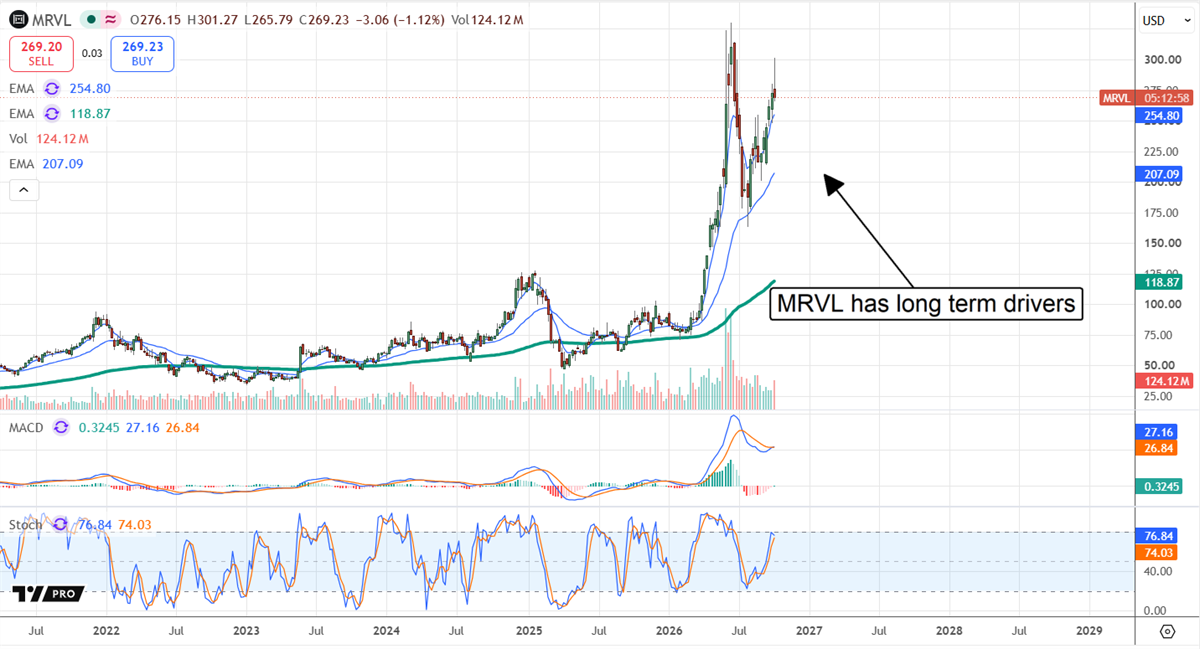
Marvell (NASDAQ: MRVL) raised eyebrows at its Oct. 6 Investor Day by lifting long-term guidance. The company raised guidance for its next fiscal year by 10%-20% and more aggressively raised longer-term forecasts, targeting a 4x increase over the next four years and indicating broad-based strength in its data center products.
While not an increase to this quarter’s estimates, it reaffirms the trends in place, including robust growth and acceleration driven by industry-wide demand. Marvell’s specific strengths lie in its custom silicon and optical interconnect products. It helps clients build specialized AI factories, removing data bottlenecks so they can monetize the investment.
Marvell’s analyst trends are more than suggestive, with earnings estimates moving higher alongside a wave of post-Investor Day price-target increases. They’ve lifted the consensus, setting a high bar, but several new targets sit well above the average target.
The bank that cut Bitcoin 3 times just reversed (Ad)
On the first day of October, one of the biggest banks in the world changed its mind about Bitcoin. Citigroup raised its 12-month target from $82,000 to $113,000.
This year, Citi cut its Bitcoin target three separate times. $143,000. Then $112,000. Then $82,000. Now, on day one of crypto's strongest month, it's going the other way.
Banks don't flip like that on a hunch. They flip when the data forces them to. And when markets heat up, one thing rises before almost anything else: trading.
CPU Strength Signals the Age of Inference
Inference reached a critical turning point this year, overtaking model building as the number one demand driver for AI infrastructure. It is expected to continue taking share over time, topping 4x the modeling demand by 2030, and this is being reflected in CPU demand. Inference, such as that driven by Meta’s (NASDAQ: META) Muse personal agent, requires lots of feedback, thought processes, and loops, which require complex orchestration. CPUs provide the orchestration layer and are in high demand because they enable this large, growing market.
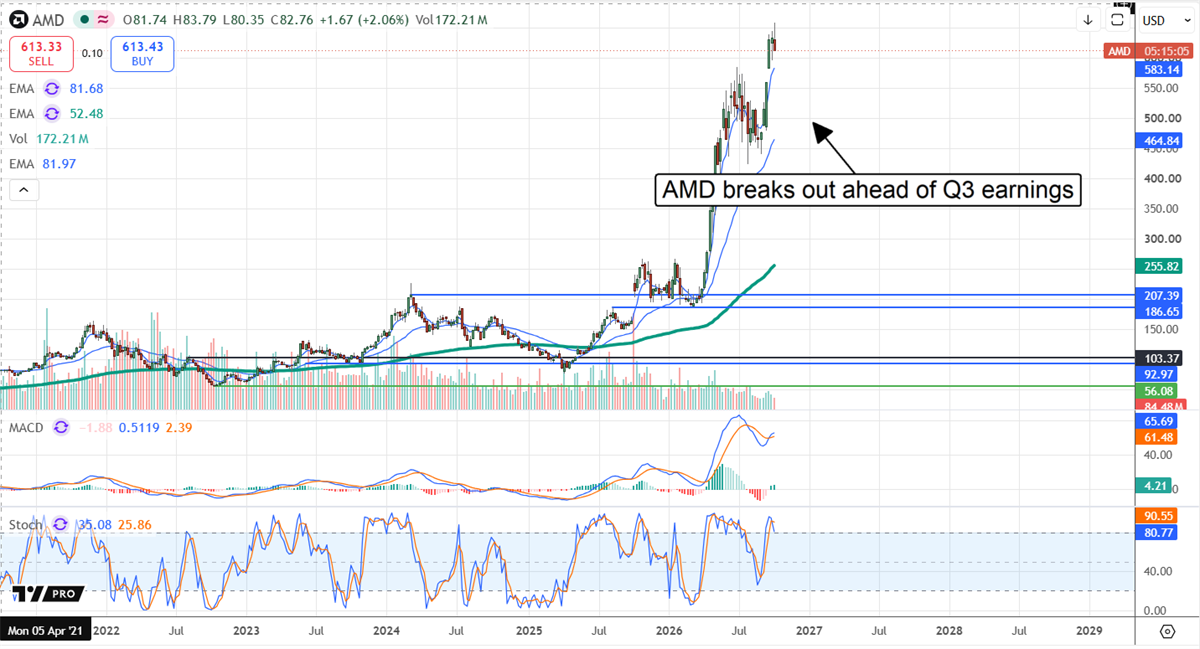
Analysts, meanwhile, are raising their targets and expectations for companies like Intel (NASDAQ: INTC) and Advanced Micro Devices (NASDAQ: AMD), which command the CPU market. They cite an expanding total addressable market (TAM), sold-out capacity, and the underlying driver—an AI factory buildout. Each AI factory drives demand for numerous inference-focused facilities, underpinning demand for AI infrastructure and security across the ecosystem.
Intel’s analyst trends and AMD's analyst forecasts are bullish, particularly around AI-driven demand and higher revenue expectations. With AMD also expected to report its first rack-scale sales, it is positioned to lead in growth and outperformance. AMD's Helios systems are already in production, with deployments beginning in the second half of 2026. Analysts forecast only moderately high growth for AMD over the next five to six quarters, peaking in the low triple-digit range, which seems unlikely given the trends. A more likely scenario is that AMD’s Helios launch triggers a wave of demand not yet priced into its stock or that of its ecosystem partners.
Read More
- 3 Stocks Chopped in Half: Why These Drops May Be Structural, Not a Dip
- Federal Reserve Reveals Disturbing New Plan To Control Your Money (From Weiss Ratings)
- Home Depot and Lowe’s Hit 52-Week Lows—But Analysts Aren’t Giving Up
- Beginner’s Guide to Gold (From Goldco Direct, LLC)
- Utilities Are Bouncing Back—These 2 Giants Could Signal the Next Big Sector Rally
- Why Wall Street Expects Even More From SanDisk After Its 575% Rally
- The Grocery Shelf Battle Is Changing—Who Comes Out Ahead?
Stay Ahead of the Market
The best investment opportunities don't wait. Get our research and stock ideas delivered straight to your smartphone—so you never miss a market-moving opportunity. Our text alerts ensure you see timely stock ideas and professional research reports instantly, whether you're in a meeting, commuting, or away from your desk.
