
Financial legend: “This is bad, really bad...” (From Weiss Ratings)
Key Points
- Bloom Energy's Q3 results show that Oracle's force majeure notice on its Jupiter project has minimal impact, since it represents only about 10% of a growing 25GW backlog.
- Bloom Energy raised guidance for the third consecutive quarter after reporting $1.24 billion in revenue, up 138.9% year over year, with expanding margins and earnings beats.
- Analysts remain bullish with a Moderate Buy rating and significant upside potential, even as share dilution and broader market corrections weigh on recent stock performance.
- Special Report: Nvidia pays a tiny dividend but this AI fund pays weekly (From Investors Alley)
Bloom Energy’s (NYSE: BE) Q3 earnings report shows strong growth despite uncertainty surrounding Oracle’s (NASDAQ: ORCL) force majeure notice. While a headwind, it is offset by numerous tailwinds, and investors must not get this wrong: Bloom's broader growth outlook does not depend solely on Oracle's Project Jupiter, although any significant delay or cancellation would still carry risks.
The project represents roughly 2.4 GW, or about 10% of the 25 GW of potential deployments Bloom has identified, rather than its contracted backlog, which is growing and diversifying across industrial applications. Bloom has other clients to sell to.
Oracle’s lean into Bloom Energy fuel cells did what it needed to do for the business: validate them and put them in the spotlight. reported visibility into about 25 GW of potential deployments in Q2, underpinned by a growing number of clients. The critical detail is that Bloom's fuel cells, while not mobile, are modular, portable, easy to install, and production capacity is highly divertible. Oracle’s headwind could become a tailwind for another project, which may now receive its cells sooner than expected.
And the status of Oracle’s Jupiter New Mexico project? The pipeline intended to supply the center is now expected to enter service in February 2027, nearly six months later than originally planned. Oracle and Bloom have since confirmed the deal remains in place, but risks remain. The hang-ups include land and air quality, with New Mexico regulators pushing back against pipeline routes and environmental impact. As it stands, the issues are under review, but the project faces numerous legal challenges, not just those impeding the gas and power. The biggest risk is to Oracle, which took on billions in debt to fund its AI ambitions. While Jupiter is not directly tied to the debt increase, monetizing the asset is critical to its outlook.
Trump goes "all-in" on Grand Canyon energy breakthrough (Ad)
A drilling crew near the Grand Canyon uncovered a clean energy well producing nearly eight times the output of Saudi Arabia's largest oil field, with potential to last two million years.
While the One Big Beautiful Bill Act eliminated federal credits for solar, wind, and EVs, this energy source was reclassified alongside oil and nuclear power and given eight years of tax credits. Google signed a 15-year contract, and Bill Gates committed $100 million.
One company controls the entire supply chain behind this discovery.
See the ticker behind this Grand Canyon energy breakthrough now
Bloom Energy's Q3 Revenue Surges as Guidance Climbs Again
Bloom Energy had a very strong quarter, reporting $1.24 billion in net revenue, up 138.1% year over year (YOY) and nearly 16% above expectations. Product sales drove the strength, up 179.4%, with strength in the services and other segments. More importantly, volume leverage is clear in margins: gross margin expanded by more than 400 basis points, adjusted operating margin more than doubled from 8.9% to over 20%, and adjusted earnings per share rose to 94 cents, up 79 cents and 25 cents above forecast.
The catalyst, however, is the guidance. Quarterly strengths and production trends led management to raise guidance for the third consecutive quarter. Revenue is now expected to be $4.5 billion at the midpoint this year, a 122% increase from last year, about 9% above the consensus target, with an equally strong earnings forecast. Earnings are expected to be $3.25 per share at the midpoint, more than four times the 2025 adjusted result, a forecast that could be exceeded.
One reason future results may exceed expectations is a new deal with American Electric Power Company (NASDAQ: AEP). Headquartered in Ohio, it serves 11 states, but the new 702-megawatt project is planned near Cheyenne, Wyoming, to serve Google, a subsidiary of Alphabet (NASDAQ: GOOGL). The Bloom Energy deal combines its natural gas-fueled, noncombustion fuel cells with planned carbon capture to provide near-zero-emission power for Google data centers. While not immediately accretive, it reflects broader acceptance of Bloom Energy's technology and its growing importance in the distributed, colocated, lower-emissions energy ecosystem.
Wall Street Sees Upside, But Bloom Energy's Risks Remain
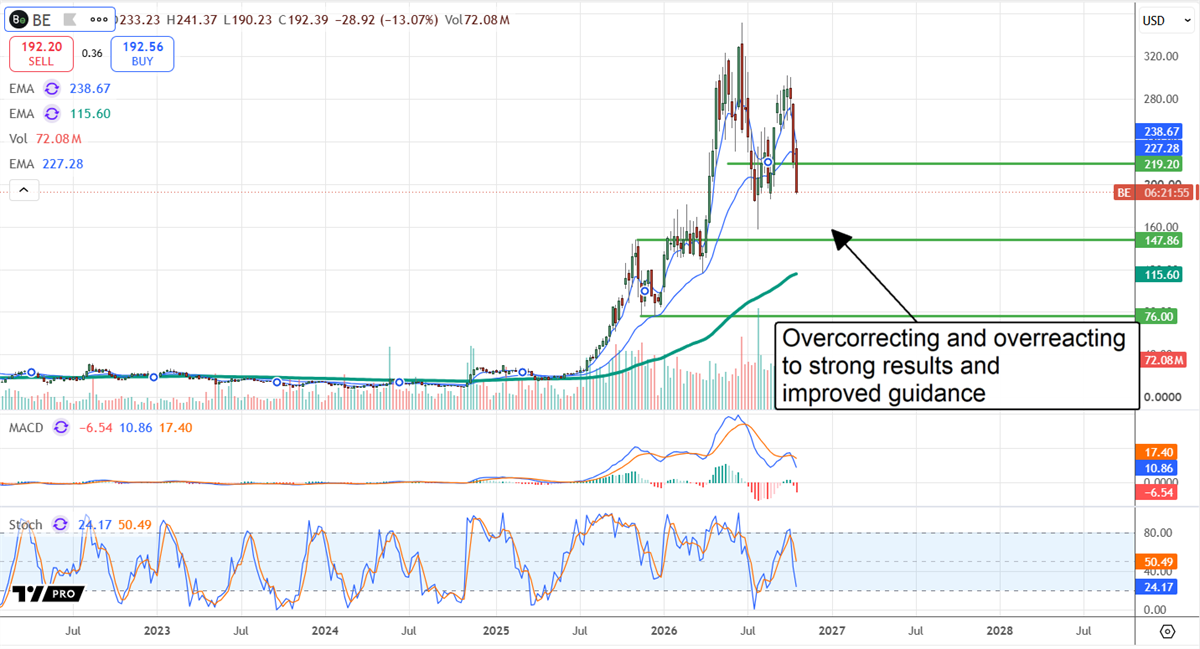
Analyst trends have been bullish all year, with coverage rising, sentiment firming, and price targets rising; post-earnings price-target changes have been mixed. Analysts maintain a consensus Moderate Buy rating on Bloom Energy, with price targets suggesting about 20% upside on average and more than 60% at the high end, despite the stock's recent decline.
The takeaway is that forces beyond the analysts are also in play, including the recent S&P 500 Index addition. It triggered an accumulation wave within an already-correcting market. Up about 2,000% over two years at its high, the market was already pricing in future strength and needed a correction. The narrative today is that the company is still outperforming, still driving a bullish outlook, and setting up for another upswing in its share price. The catalysts are numerous, but the most powerful is advancing the Jupiter project or capturing a deal to offset it.
The biggest risk to investors is dilution (also a factor in stock price action). The company’s capacity ramp costs money and is being funded, at least in part, with share sales. The bad news is that outstanding shares increased by about 5.5% from year-end 2025 through Q3 2026, but there is an upside. Balance sheet highlights reflect a robustly growing, solvent business, with execution as its biggest challenge. Balance sheet details include a flat cash position, increased receivables, contract assets that grew 4x, and higher inventory, outpacing liability gains and leaving equity up 2.5x. The likely outcome is that Bloom Energy’s backlog continues to grow, it converts contracts into capital, and it fuels its flywheel, which is building momentum.
Featured Stories
- Why Western Digital's AI Storage Boom Defies the Chip Sell-Off
- Do NOT Buy SpaceX – Do This Instead (From Stansberry Research)
- Grand Canyon Education Strengthens Its Outlook, But Wall Street Remains Divided
- Write this ticker down before Dec. 18 (From Brownstone Research)
- Amex Stock Slides on Job Cuts, But the Real Story Is Macro
- Chefs' Warehouse Has Rallied 76%—Can the Stock Keep Climbing?
- MarketBeat Week in Review – 10/19 - 10/23
Stay Ahead of the Market
The best investment opportunities don't wait. Get our research and stock ideas delivered straight to your smartphone—so you never miss a market-moving opportunity. Our text alerts ensure you see timely stock ideas and professional research reports instantly, whether you're in a meeting, commuting, or away from your desk.
