
In partnership with

Can’t Buy the Next AI IPO Yet? Watch 3 Stocks.

Wall Street is preparing for what could become one of the biggest AI IPOs in history. But ordinary investors may have to wait until shares begin publicly trading to participate directly.
Meanwhile, three publicly traded companies could offer exposure to the AI infrastructure and investment boom surrounding Anthropic. Two are familiar names. The third is a lesser-known company that many investors haven't connected to the story.
A new, free briefing reveals all three tickers, potential entry prices, and a bonus fourth company holding thousands of patents tied to the AI race.
See the three stocks before the next wave of attention arrives. Free briefing, no credit card required.
Last note from me on this (From The Cycle Code)
Key Points
- Cigna, Toll Brothers, and General Motors trade at relatively low valuations despite strong fundamentals and favorable analyst ratings, suggesting the market may be undervaluing them.
- Cigna raised its full-year adjusted earnings outlook and has cut its share count by a fifth over five years while trading at about 9x forward earnings.
- General Motors beat Q3 2026 revenue and earnings expectations, approved a new $20 billion buyback, and trades around 6x forward earnings despite tariff and EV headwinds.
- Special Report: Green, red, gold (From The Cycle Code)
Favorable analyst ratings don't necessarily mean that a company's share price will go up. Sometimes the market lags behind a bullish Wall Street assessment, which can leave quality companies at relatively low earnings multiples even as they build up Buy ratings. The key is for investors to be able to pick out those companies before the broader market catches on.
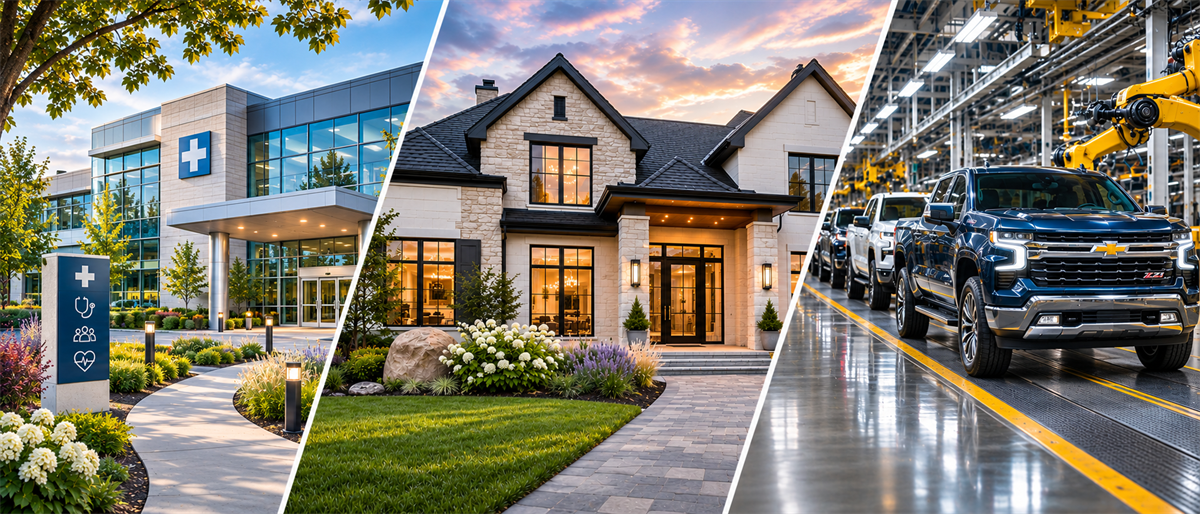
Cigna Group (NYSE: CI), Toll Brothers Inc. (NYSE: TOL), and General Motors Co. (NYSE: GM) could all fit that description. These are firms with notable strengths including substantial free cash flow, conscientious share count management, and comparably low valuations. Each offers a unique but compelling case for why the broader investor world may be missing an opportunity to buy before prices increase.
After the midterms: review your portfolio exposure (Ad)
The vote ended. Your portfolio risks remain. Several tickers can share the same exposure. Explore our five-stock portfolio-resilience report, then compare the ideas with what you already own. Start the review before reacting to the next headline.
Cigna Combines Low Valuation With Strong Buybacks and Improving Earnings
Health services giant Cigna announced almost 6% year-over-year (YOY) revenue growth and wins on both the top and bottom lines for Q3 2026, but the biggest news from the company's latest earnings report may be an increase to its full-year adjusted earnings outlook to at least $30.60 per share, up from a floor of $30.45.
Evernorth, which includes the company's pharmacy benefit and specialty businesses, has continued to drive growth. However, it will likely face new pressures in the coming quarters due to industry-wide rebate shifts and an overall reduction in the number of employers offering coverage for GLP-1 drugs for weight loss.
Nonetheless, between pharmacy benefits and the company's broader specialty and care services business, Cigna expects to see at least 10% adjusted earnings per share (EPS) growth in 2027 from its ongoing businesses.
Cigna trades at a relatively modest 9x forward earnings, a sizable discount to the broader market. The company has capitalized on this by reducing its share count by a fifth over the last five years, including approximately $500 million in repurchases during the first nine months of 2026. This has been made possible in part by the 2025 sale of its Medicare Advantage business.
An improving earnings outlook combined with strong buybacks and valuation may point to an overlooked stock, but Wall Street sees CI shares as a Moderate Buy overall. However, risks remain: besides pressures on its pharmacy benefit business, Cigna is preparing to roll out its Signature pharmacy pricing model to fully insured customers in 2027, and costs continue to rise.
Toll Brothers' Customer Base Is Resilient, Even If the Market Hasn't Noticed
Homebuilder stocks have faced a difficult macro environment as affordability pressure and waning consumer sentiment have weighed on performance. However, Toll Brothers is in a unique position thanks to its luxury brand and customer base: its homes sold for an average of about $996,400 in Q3 2026, and the company's affluent buyers may have been better able to weather the inflation storm in recent years.
The company's luxury move-up segment accounted for 61% of Toll Brothers' Q3 2026 home sales revenue, and a 25% cash-purchase rate helped give management the confidence to reaffirm its full-year outlook for fiscal 2026. Having $3.3 billion in liquidity and a net debt-to-capital ratio of 15.6% as of the end of Q3 also helps.
That said, TOL shares still trade around 11.5x forward earnings and with a modest premium to book value. By comparison, rivals like NVR Inc. (NYSE: NVR) and Lennar Corp. (NYSE: LEN) both trade above 17x forward earnings. This may suggest that the market isn't giving Toll enough credit for its resilient customer base and that the stock remains undervalued in the industry.
The firm has also ambitiously reduced its share count, repurchasing hundreds of millions of dollars of stock annually in recent years. This puts investors in the position to benefit if Toll sees its most natural upside catalyst come to pass: a reduction in mortgage rates. Lower rates would mean a larger pool of potential buyers and would help to reduce the need for the company to offer incentives.
After the midterms: question your stock shortlist (Ad)
The vote is over. Is your watchlist too familiar? Explore seven hidden-gem stock ideas beyond your usual tickers. Read our free report, then examine each business and its risks before deciding what deserves a closer look.
General Motors Faces Tariff, Inflation, and EV Headwinds, But Growth Is Strong
Despite its size and prominence, General Motors demonstrates a major disconnect between fundamentals and valuation. The company trades at around 6x forward earnings, a valuation which has prompted a share count reduction of about a third in the last four years. For a firm with significant liquidity, this means General Motors can also continue to offer a modest quarterly dividend.
On the earnings side, GM has performed well: it beat analyst revenue expectations for Q3 2026 by $1.2 billion and also came out a cent ahead of EPS predictions. The company boosted its full-year adjusted automotive free cash flow expectations while approving a new $20 billion share repurchase authorization.
The question for investors is whether GM's ability to grow earnings and cash while returning capital to investors makes the stock attractive despite the risks facing the industry. Inflation has struck automotive firms particularly hard, and electric vehicles are disrupting the company's longstanding business model. The company continues to navigate difficulties in China and with tariffs.
If GM is able to continue its buyback program and sustain its pricing in the truck and SUV space, it may be able to realize analysts' prediction of more than 14% in upside.
Recommended Stories
- Keeping AI Cool: AAON Rides the AI Heatwave to Record Growth
- I'm handing you this stock today (From Behind the Markets)
- AST SpaceMobile Has a New Rocket Plan, But Its Cash-Burn Problem Isn't Going Away
- Former White House Insider Issues Crazy Prediction: Dow 100,000 (From Paradigm Press)
- Powering Up the Moon: Redwire’s $40 Million NASA Award
- Can Constellation Energy's Contracts Power a Stock Rebound?
- Why Apple Stock Looks Like a Safe Haven After the Midterms
Stay Ahead of the Market
The best investment opportunities don't wait. Get our research and stock ideas delivered straight to your smartphone—so you never miss a market-moving opportunity. Our text alerts ensure you see timely stock ideas and professional research reports instantly, whether you're in a meeting, commuting, or away from your desk.
